The highest offer doesn't always win. Sellers are weighing risk as much as price, and a slightly lower offer that's sure to close can beat a bigger one that might fall apart. That's good news if you're competing against cash or deeper pockets.
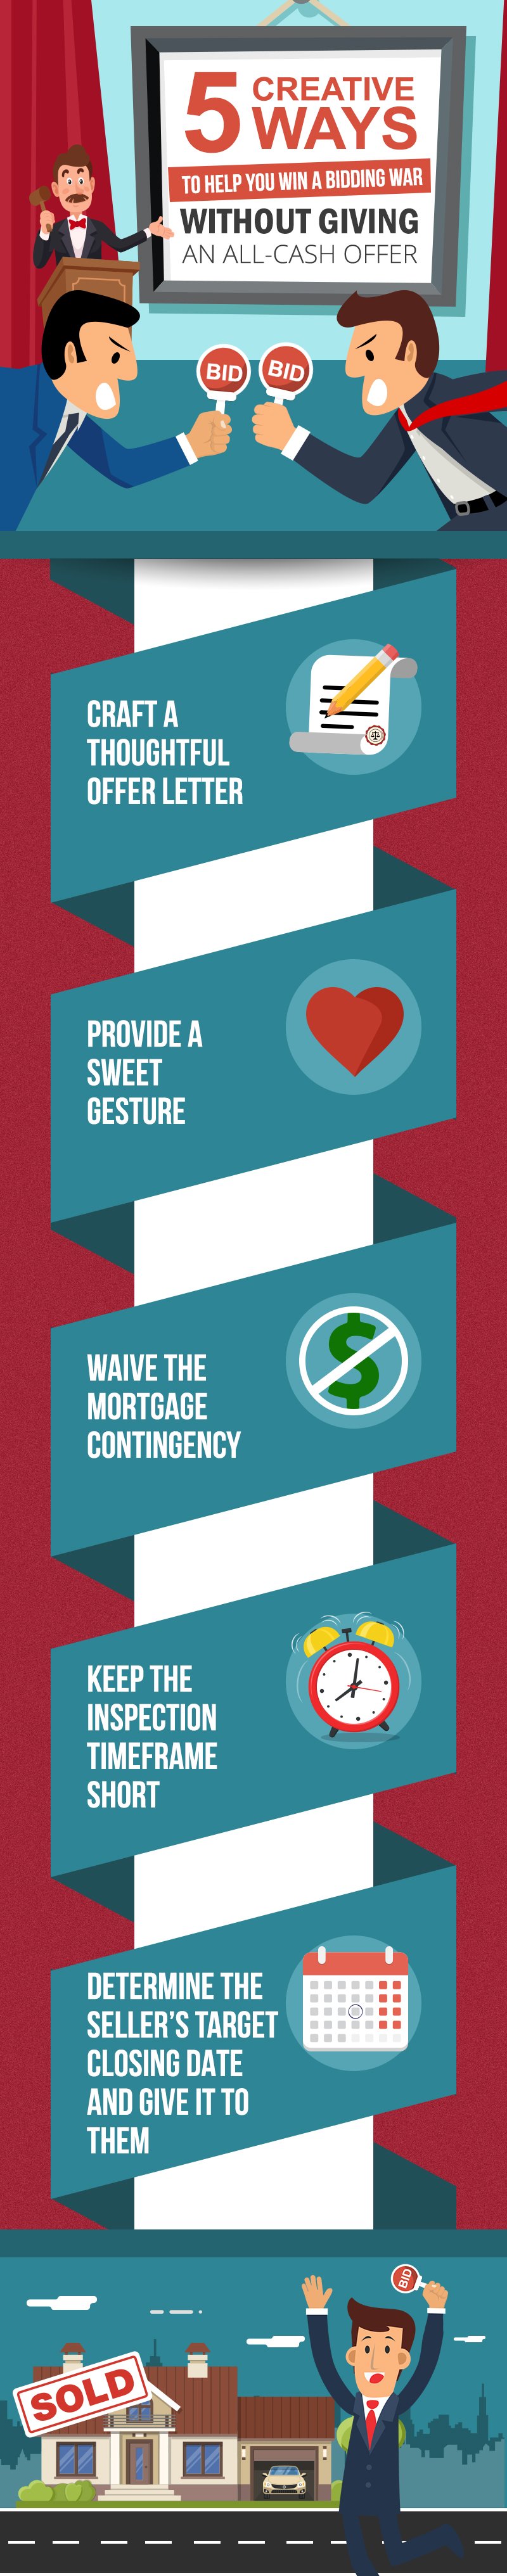
Here are five ways to strengthen an offer in a multiple-offer situation without simply raising your price, and where each one can backfire.
Before any of these, get the foundation right: a pre-approval that an underwriter has already reviewed, and a lender who answers the phone when the listing agent calls to check on you. In a competitive East Bay market, those two things alone move an offer up the stack. Here's what a real pre-approval includes.
1. Make your offer easy to say yes to, and skip the personal letter
Buyer love letters used to be standard advice. Today many agents steer clients away from them, because personal details about who you are can expose sellers to fair housing claims, and many listing agents won't pass them along. A better approach is a short cover note from your agent that sums up why your offer is strong: your approval, your down payment, your timelines and how reachable your lender is.
Clean paperwork matters too. A complete offer with proof of funds, the approval letter and every disclosure acknowledged makes the listing agent's job easy, and they notice.
2. Sweeten the terms, not the sentiment
The gestures that really move sellers are financial and practical:
A meaningful earnest money deposit. It shows you're committed. In California the deposit usually goes into escrow within a few business days of acceptance. Know when it's at risk, which mostly comes down to your contingency dates.
Covering costs the seller would normally pay, where that's negotiable.
A shorter escrow, if your lender can actually close on that timeline.
Ask your agent to find out what matters most to this particular seller. Sometimes it's speed. Sometimes it's certainty. Sometimes it's time to find their next home.
3. Shorten your loan and appraisal contingencies, carefully
Waiving the loan contingency entirely was a popular way to compete with cash, and it's risky. If your financing falls through after you've removed it, your deposit is exposed. A safer version is a shorter loan contingency backed by a fully underwritten approval.
The appraisal is the other common sticking point. If the home appraises below your price, the lender bases your loan on the lower value, and you'd need to cover the gap in cash or renegotiate. Some buyers offer to cover a set amount of any appraisal gap. Only do that if you have the cash and are truly comfortable with the price.
In California, contingencies don't simply disappear when the clock runs out. You remove them in writing, and once you do, your deposit is more at risk if you back out. More on how contingencies work.
4. Keep the inspection period short, but don't skip it
Waiving inspections can save a few days and look attractive to a seller. It can also mean buying a foundation, sewer line or roof problem with no way out. A better approach:
Read the seller's disclosure package before you write. In much of the East Bay, sellers provide home and pest inspections up front.
Have your own inspector walk the home before you submit, if the seller allows it.
Then offer a short investigation period you can actually meet.
Here's how to tell what really matters in an inspection report.
5. Match the seller's timeline
Many sellers are buying their next home at the same time. A closing date that lines up with their purchase, or a short rent-back that lets them stay in the home for a few weeks after closing, can be worth more to them than a higher price. Ask the listing agent directly what timing would help.
If you're the seller this time
This works in reverse. When you're reviewing offers on your own home, the cleanest offer isn't always the biggest number. Look at the approval behind it, the contingency timelines and how likely it is to close on time, especially if you need that sale to fund your next purchase. See buying before you sell.
What to do next
Line up a fully reviewed approval, know your walk-away number before you write and decide in advance which terms you're willing to bend on. When you're ready, search homes across the East Bay.
Competing for a home and want help shaping a stronger offer? Call or text 925-876-0876, or reach us here.
Pacific Residential Partners | NMLS #633518 | DRE #02101650