The stretch between an accepted offer and getting your keys is where most of the stress lives, mostly because nobody explains the order of things. Contingencies are the rules of that stretch. They're conditions written into the contract that have to be satisfied, or formally removed, before the sale moves forward, and they decide when you can walk away and keep your deposit.
Here's how contingencies work in a California purchase, how they're removed and what happens in escrow, step by step, for buyers and sellers alike.
The contingencies in most California purchases
Every contract is negotiated, but most residential purchases in California use the standard purchase agreement, and many of its contingency periods default to 17 days from acceptance unless the parties agree otherwise. The common ones:
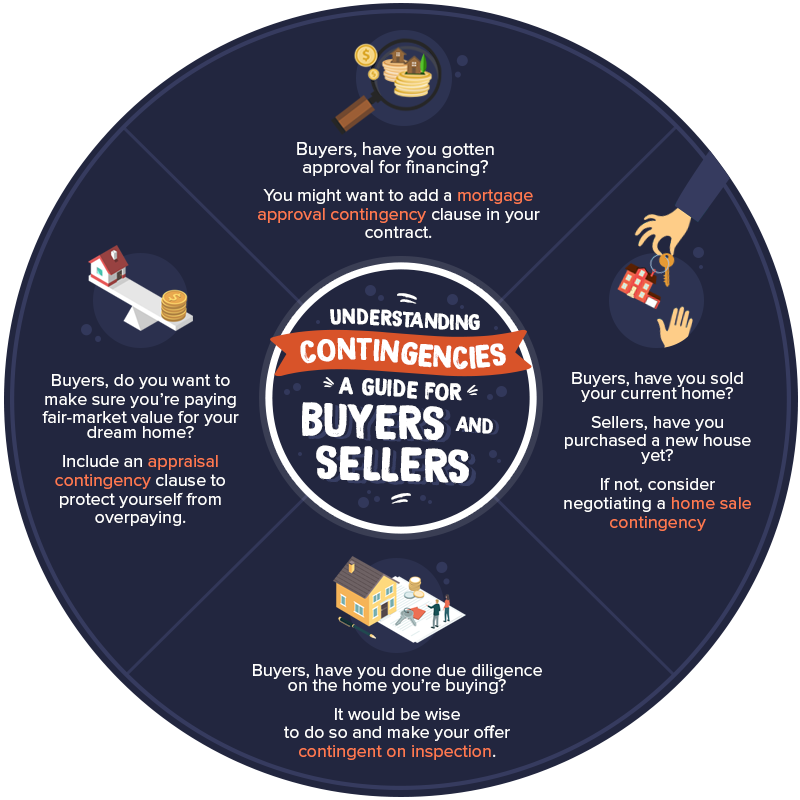
Investigation (inspection) contingency. Time to inspect the property, review the seller's disclosures, check permits, get an insurance quote and look into anything else that affects your decision. This is where you ask for repairs or credits.
Loan contingency. Protects you if your financing falls through despite a good-faith effort. It's only as strong as your approval, so it pairs best with a fully underwritten one.
Appraisal contingency. Protects you if the home appraises below the purchase price, giving you room to renegotiate, cover the gap or cancel.
Review of documents. Time to read the preliminary title report, HOA documents if it's a condo or planned community, and other reports.
Sale of the buyer's property. Makes the purchase depend on the buyer selling their current home. Sellers often accept it only with the right to keep marketing and accept a backup offer.
How contingency removal works in California
In California, contingencies don't simply expire when the time runs out. The buyer removes them in writing. If a deadline passes without a removal, the seller can deliver a notice asking the buyer to act, and if the buyer doesn't respond in time, the seller may be able to cancel.
Once you remove a contingency, you generally can't use that issue to back out and recover your deposit. If the contract includes a liquidated damages clause and both parties initialed it, the amount a seller can keep if an owner-occupant buyer defaults on a one-to-four unit home is capped at 3% of the purchase price. Know every date in your contract, and don't remove a contingency until you're confident the inspection, appraisal and loan are where they need to be. More on earnest money deposits.
Escrow, step by step
Deposit and opening escrow. Your earnest money goes into escrow, usually within a few business days, and the title company starts its work.
Inspections. These happen early. You review reports and disclosures and decide whether to ask for repairs or credits. See how to read an inspection report.
Appraisal and loan approval. The appraisal is ordered and your lender works the file toward final approval. Answer document requests the same day.
Contingency removals. You sign to remove each contingency as it's satisfied.
Insurance and Closing Disclosure. Homeowners insurance is bound, and you receive your Closing Disclosure at least three business days before you sign loan documents.
Signing and funding. You sign, wire your funds after confirming the instructions by phone with escrow, and the lender funds the loan.
Final walkthrough, recording and keys. Confirm the home's condition and agreed repairs, then the deed records with the county. Here's a final walkthrough checklist.
Ask your agent and lender for a written timeline with dates at the very start. If someone can't tell you what happens next, that's worth knowing early.
For sellers
Contingencies are where an accepted offer can still come apart, so read them as carefully as the price. Shorter periods, a fully underwritten approval and a buyer who doesn't need to sell first all reduce your risk. If you're selling to buy, line up your own purchase timeline with the buyer's contingency dates so neither side gets stuck. More on buying before you sell.
What to do next
Before you write an offer, decide which contingencies you need and how long each should be. Then build your schedule backward from your closing date. When you're ready, search homes across the East Bay.
In escrow and want a second set of eyes on your dates? Call or text 925-876-0876, or reach us here.
Pacific Residential Partners | NMLS #633518 | DRE #02101650